What does the Renters’ Rights Bill mean for residential valuation?
Key Points:
Abolition of fixed-term ASTs creates valuation uncertainty
Mixed-use properties face amplified risk
Historic comparables may lose reliability
Lenders monitoring but haven't changed criteria yet
Market entering period of recalibration
The Renters’ Rights Bill has now passed, marking the most significant overhaul of the private rented sector in a generation. Much of the public discussion has centred on what the reforms mean for tenants and landlords, but a quieter and potentially more consequential shift is taking place within the world of property valuation. The abolition of fixed-term ASTs in favour of open-ended periodic tenancies could fundamentally alter the assumptions that valuers and lenders have relied on for years. What remains uncertain is how far this shift will go and how quickly the market will respond.
This raises an important question for the sector: are we on the verge of a major redefinition of residential investment risk, or will the impact be less dramatic than many anticipate?
From Residential Predictability to Commercial Volatility?
For decades, residential valuations have been underpinned by the stability that fixed-term tenancies provided. These contracts offered reliable income patterns and clear rental cycles, which in turn gave valuers a solid foundation for modelling returns. Even properties with more complex characteristics, such as flats above commercial units, could be assessed with some predictability if the tenancy history looked steady.
That landscape may now be shifting. With open-ended periodic tenancies, income projections are no longer tied to fixed terms, and turnover risk becomes harder to forecast. Some in the industry believe this introduces a level of volatility that brings residential investment closer to the commercial sector, where income fluctuations, tenant movement and operational unpredictability are all part of the valuation process. Others argue that the fundamentals of residential demand will remain strong enough to offset these risks.
It is not yet clear which view will win out, and this uncertainty alone may influence investor behaviour in the short term.
What Happens to Properties Above Commercial Premises?
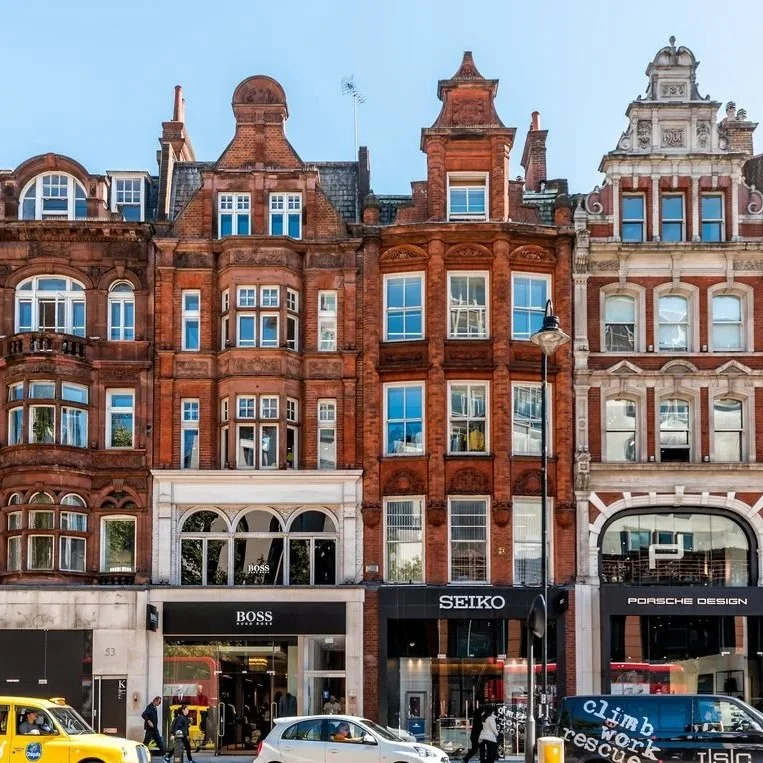
One of the most interesting questions relates to mixed use assets and in particular flats positioned above commercial units. These properties already sit in a more sensitive part of the market due to issues such as noise, extraction plant, food uses and general trading activity. They often attract a narrower tenant pool and lenders tend to view them with greater caution.
The shift to periodic tenancies could amplify these existing challenges. If tenants can leave more easily, their tolerance for disturbances from commercial uses below may reduce, leading to more frequent turnover and potentially higher void periods. Some valuers are already questioning whether yields for these assets will begin to soften as investors seek a greater buffer against this uncertainty. Others suggest the opposite possibility that these assets could become more attractive to opportunistic investors who see any price adjustment as a buying opportunity.
The market has not yet decided which direction it will go.
Comparable Evidence: Still Reliable or Already Outdated?
Another issue quietly concerning valuation professionals is the reliability of comparable evidence collected under the old AST system. If income patterns change as a result of periodic tenancies, historic sales and yield benchmarks may no longer provide a direct comparison. Mixed use properties already suffer from a lack of consistent evidence and this could widen the gap further.
Will valuers need to place greater emphasis on income modelling rather than traditional direct comparison? Will lender requirements evolve to reflect this shift? Or will the market settle quickly enough that comparables remain broadly usable? The answers are not yet clear, and this uncertainty may itself become a factor in valuations over the coming 12 to 24 months.
Lenders: Watching and Waiting
Lenders have not yet made formal changes to their criteria, but most are monitoring the situation closely. The key unknown is how they will respond once the new tenancy system is in force and real world patterns begin to emerge. Will they reduce loan to value ratios in sectors where income risk appears higher, such as flats above commercial uses? Will they require more detailed commentary from valuers on turnover assumptions and void risk? Or will the overall impact be moderate enough that lending continues largely as before?
The industry does not yet have a clear answer, and this hesitation may influence sentiment as investors try to anticipate how funding conditions might evolve.
A Market on the Edge of Change
What makes the Renters’ Rights Bill so significant for valuers is not only the policy shift itself but the number of open questions it creates. How quickly will tenant behaviour adapt? How will institutional investors respond compared with smaller landlords? What will happen to complex assets such as mixed use units and secondary flats in high street locations? And perhaps most importantly, will the market find a new equilibrium quickly, or will this be the beginning of a longer period of recalibration?
The coming months and years will provide the answers, but for now the valuation landscape sits at an interesting crossroads. This is exactly the type of moment that invites discussion and debate within the industry, and the implications may be broader than many people first assumed.